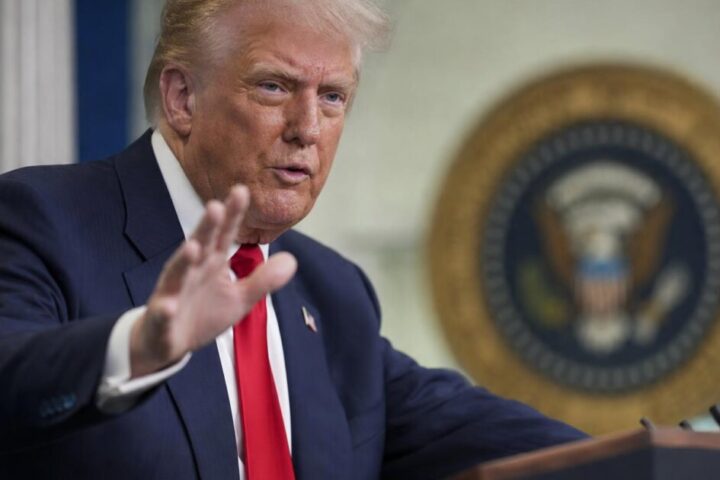
President Donald Trump signed an executive order directing banks and federal financial regulators to factor in customers’ immigration status when evaluating potential financial risks. The order, titled “Restoring Integrity to America’s Financial System,” marks one of the administration’s most direct moves to restrict non-citizens’ access to U.S. financial institutions.
Under the order, the Treasury Secretary and federal regulators must provide banks with guidance for identifying customers whose profiles or transactions may suggest risks including money laundering, terrorism financing, and labor trafficking. The administration says the move is consistent with the 1970 Bank Secrecy Act.
Red Flags Targeting Immigrant Banking Habits
The order lays out specific “red flags and typologies” that banks should watch for. These include repetitive cash withdrawals, use of shell companies to obscure account ownership, and platforms used for off-the-books wage payments.
Notably, the order flags the use of an Individual Taxpayer Identification Number, or ITIN, in place of a Social Security number when opening accounts or conducting certain transactions. ITINs are available to anyone regardless of immigration status and are widely used by non-citizens to file and pay taxes. Critics warn the measure could make it significantly harder for undocumented immigrants, and even legal non-citizens, to access basic financial services. According to a study by the Urban Institute, lenders issued roughly 5,000 to 6,000 mortgages to ITIN customers, a relatively small share of the broader market. You can read more about Trump’s financial system executive order and the specific provisions it targets.
“President Trump is taking action to restore integrity to America’s financial system, cracking down on illicit activity that threatens national security and ending the extension of credit to high-risk borrowers that American citizens are forced to subsidize,” a White House fact sheet stated. The administration also argued that banks extending mortgages and credit cards to undocumented immigrants pushes “costs on to American consumers in the form of higher fees and interest rates,” though economists broadly attribute higher borrowing rates to benchmark rates, bank funding costs, and individual credit factors.
Broader Deregulation and the JPMorgan Dispute
The order directs the Treasury to explore regulatory changes that would allow financial institutions to more easily collect customer data, including immigration status and employment authorization. The White House cited documented Chinese-linked money laundering networks as evidence that gaps in identification practices have allowed criminal networks to exploit U.S. banks.
The move comes as Trump pursues a $5 billion lawsuit against JPMorgan Chase and its CEO over the closure of his accounts following the January 6, 2021, Capitol riot. JPMorgan responded in January, saying, “Our company does not close accounts for political or religious reasons. We do close accounts because they create legal or regulatory risk for the company.”
What Comes Next for Banks and Non-Citizens
Banks are already generally reluctant to lend to ITIN holders, and government-backed mortgage insurers Fannie Mae and Freddie Mac typically do not insure loans for ITIN borrowers. The new order is expected to deepen that reluctance across the industry.
Separately, the Treasury Department had previously signaled plans to reclassify certain refundable tax credits as “federal public benefits,” which could further limit non-citizens’ eligibility. Together, the measures represent a broad administration push to limit immigrants’ participation in U.S. financial systems, even as the White House simultaneously pursues deregulation benefiting non-traditional financial firms and has pledged to make the United States the “crypto capital of the planet.